Buying your first home
Down payment rules, the stress test, FHSA and RRSP withdrawals, and what you can genuinely afford.
A clearer path home
Buying, renewing or refinancing in Canada? We'll show you what your options actually mean — the payment, the term, the penalty — before you commit to any of them.
Rates change weekly. We'll tell you which one is actually right for you.
Talk with an advisorTrusted by Canadian homeowners since 2009
Why we exist
Most people are handed a rate and asked to sign. We do it the other way around: we explain what you're choosing between, what each option costs over the full term, and what happens if life changes halfway through.
Every option comes with the trade-off written next to it — in plain language, not in a rate sheet.
Penalties, prepayment limits and renewal terms are part of the conversation from the first meeting.
Not a call centre. The person who builds your file is the person who answers the phone in year four.
What we do
Six starting points. Each one opens into a conversation about your numbers — never a pre-packaged answer.
Down payment rules, the stress test, FHSA and RRSP withdrawals, and what you can genuinely afford.
Your lender's renewal letter is an offer, not a verdict. We compare it against the whole market.
Consolidating debt or accessing equity — with the penalty and the break-even calculated up front.
Rental offset, qualifying income and portfolio structure for second and third properties.
Programs for newcomers with limited Canadian credit history — and what documents to gather now.
Stated and alternative income structures for business owners, contractors and commission earners.
Payment calculator
Canadian mortgages compound semi-annually, not monthly — so most calculators are slightly wrong. This one isn't. If your down payment is under 20%, it also adds the mortgage default insurance premium to your balance.
An estimate, not an approval. Property tax, condo fees and heating are excluded.
Our approach
Before anything is submitted, you'll know your maximum, your comfortable number, and the difference between the two. That gap is where most financial stress lives — and it's the part nobody explains.
No credit check to start. The first conversation costs you nothing and touches nothing on your file.
Written comparisons. You leave with the numbers in hand, not a verbal promise.
We're paid by the lender. Our guidance costs you nothing, and we'll tell you when staying put is the better move.
How it works
You'll always know which stage you're at, what we're waiting on, and who has it.
A 20-minute call. No documents required yet.
We map what you qualify for against what you're comfortable with.
Rate, term, penalty and prepayment for every shortlisted lender.
You decide. We make sure nothing in the fine print surprises you.
Secure upload, one checklist, no re-sending the same file twice.
Live status from submission through to the lawyer's office.
Renewal reminders, equity updates and a rate review every year.
“Mortgage approved” isn't the end of the relationship. It's the start of it.
People, not portals
Forty-one licensed advisors across Ontario and British Columbia. You'll work with one of them — the same one — for as long as you hold the mortgage.
They talked us out of the cheaper rate. The penalty structure would have cost us twice the saving when we moved two years later.
First time buying anything. I understood every number before I signed, which I did not expect from a mortgage.
Self-employed for nine years and three banks had already said no. SL found the structure that worked in a week.
Where we work
High-ratio strategy, strata financing and pre-sale assignments.
Second homes, recreational property and rural lending.
Condo approvals, new-build closings and investment portfolios.
Questions
Can't find yours? Ask an advisor directly — there's no obligation attached to the answer.
Ask a questionFor standard residential mortgages, no. The lender pays us when your mortgage funds. If a file requires a private or alternative lender, any fee is disclosed and agreed in writing before we proceed — never after.
We pull your credit once, with your permission, and present that single report to every lender we approach. Our first conversation doesn't require a credit check at all.
5% on the first $500,000, 10% on the portion between $500,000 and $1.5M, and 20% above that. Below 20% overall, mortgage default insurance is mandatory and is added to your mortgage balance — the calculator above shows you exactly how much.
It depends far more on your plans than on the rate forecast. If there's a real chance you'll sell, move or refinance mid-term, the penalty difference between the two usually matters more than the rate. We'll model both against your situation.
You must qualify at the higher of your contract rate plus 2%, or 5.25%. It doesn't change what you pay — it changes what you're allowed to borrow. We'll show you both numbers so there are no surprises at the offer stage.
A pre-approval is typically same-day to 48 hours. A full approval, once documents are in, usually takes two to five business days depending on the lender and the property.
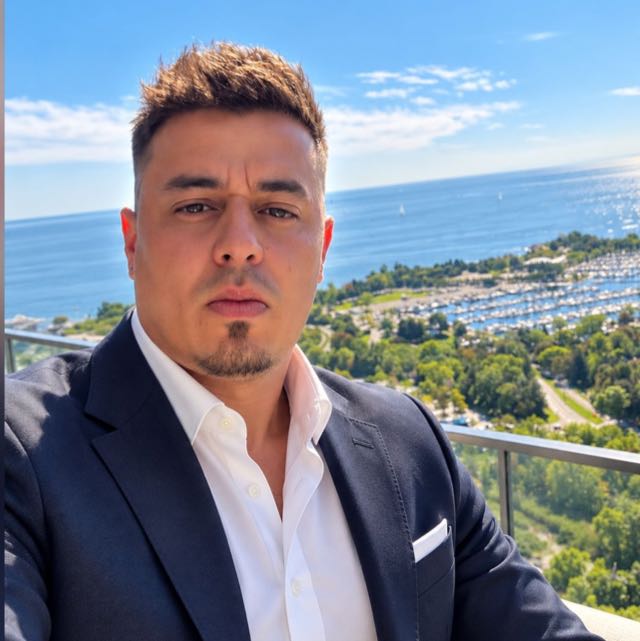
Your mortgage agent
Mortgage Agent Level 1
Start whenever you're ready
Twenty minutes, no credit check, no obligation. You'll leave the call knowing more than when you joined it — whether or not you work with us.
Advisors reply Monday to Saturday, 8am–8pm ET. No forms, no waiting on an email.